Table of Contents
1. Market Growth Projections
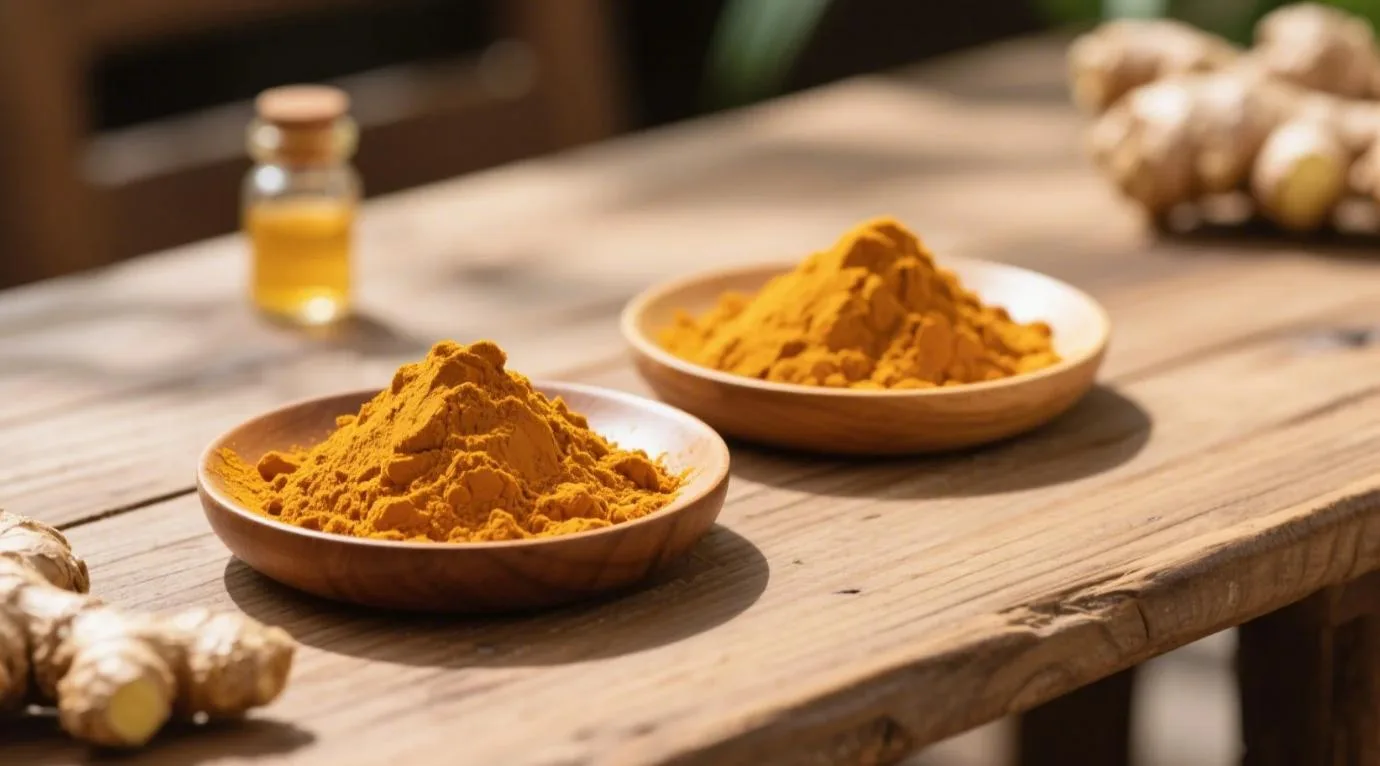
The global organic turmeric market, encompassing both turmeric extract and powder, is poised for robust growth. Valued at $9.8 billion in 2024, the sector is projected to reach $18.3 billion by 2030, reflecting a CAGR of 7.2%. This expansion is driven by a structural shift in how consumers, clinicians, and food manufacturers perceive the spice: no longer merely a culinary coloring agent, turmeric has become a mainstream functional ingredient. Rising healthcare costs, growing skepticism toward synthetic additives, and an aging population seeking preventive wellness solutions have all converged to push demand upward across every major region. Supply-side improvements in organic cultivation, coupled with more efficient extraction technologies, are making high-curcumin products accessible to a broader base of buyers than ever before, while inflation-resistant procurement strategies are pulling turmeric into long-term sourcing plans.
- Health-Conscious Consumer Demand: Over 68% of Gen Z and millennials prioritize natural anti-inflammatory solutions, with turmeric’s curcumin content linked to a 23% reduction in chronic inflammation markers. This demographic increasingly reads supplement labels, favors clean-label certifications, and is willing to pay a premium for traceable, organically grown raw materials. Social media has amplified awareness of golden lattes, golden milk, and supplement stacks, while peer-reviewed publications on curcumin’s antioxidant profile have lent scientific credibility to long-standing traditional uses. As preventive health moves from niche to norm, retailers from specialty grocers to mass-market e-commerce platforms are expanding turmeric SKUs, further accelerating volume growth and normalizing daily consumption.
- Pharmaceutical Innovation: Clinical trials validate curcumin’s efficacy in treating arthritis (34% pain reduction) and neurodegenerative diseases, with bioavailability-enhanced formulations (e.g., liposomal curcumin) capturing 22% of the nutraceutical market. Drug developers are investigating standardized extracts for metabolic syndrome, cardiovascular support, and mood regulation, while combination therapies pairing curcumin with piperine or phospholipids aim to overcome the compound’s historically poor absorption. The pipeline of investigational formulations signals that turmeric is transitioning from a supplement-aisle curiosity into a credible adjunct within evidence-based medicine, attracting both venture capital and established pharmaceutical partners seeking differentiated active ingredients.
- Regulatory Support: USDA Organic and EU certifications now cover 90% of premium turmeric products, enabling access to high-value markets like the EU and North America. Harmonized standards for residue limits, heavy-metal testing, and fair-trade sourcing have reduced buyer uncertainty and lowered barriers to entry for compliant suppliers. Governments incentivizing sustainable agriculture and import diversification have further stabilized trade flows. For B2B buyers, certification acts as a de-risking instrument: verified organic status simplifies compliance audits, supports premium positioning in competitive retail environments, and reassures downstream brands facing increasingly strict documentation requirements from regulators and retailers alike.
2. Differentiation Between Extract and Powder
A. Organic Turmeric Powder
- Applications: Dominates culinary and traditional medicine sectors, with 65% of sales from food & beverage industries (e.g., golden lattes, functional snacks). Beyond cafés and ready-to-drink beverage launches, powder is blended into baking mixes, seasoning rubs, instant soups, and wellness shots. Its familiar sensory profile and ease of formulation make it the default choice for brands entering the functional-food space. In traditional systems such as Ayurveda, whole powder remains the preferred form for teas and tonics, sustaining steady demand from heritage and artisanal producers who value minimal processing and the full-spectrum phytochemical matrix that gentle milling preserves.
- Market Share: Holds 58% of the organic turmeric market, driven by cost-efficiency ($12–$18/kg) and versatility in small-scale artisanal production. Lower price points widen the addressable customer base, from household kitchens to mid-tier manufacturers, and shorten the path from harvest to finished goods. Because powder requires comparatively modest capital equipment, cooperatives and regional mills can participate in value chains that would otherwise be dominated by large extractors, supporting rural livelihoods and distributed economic resilience across producing regions while keeping supply geographically diversified.
- Challenges: Limited curcumin bioavailability (1–2%) restricts therapeutic adoption, though cold-pressed innovations improve retention by 40%. The naturally low absorption of curcumin from raw powder means that, for clinical or high-efficacy applications, powder alone may underdeliver on expectations. Mitigation strategies include pairing with black pepper extract, micro-milling to increase surface area, and gentle low-temperature processing that preserves volatile actives. Brands that communicate these nuances transparently build trust with informed buyers seeking measurable outcomes rather than marketing claims, and position powder as an everyday wellness staple rather than a clinical intervention.
- Premium Positioning: Commands 42% market share, priced at $50–$200/kg for 95% curcuminoid concentrations. Extracts concentrate the bioactive fraction of the root, delivering standardized potency that powder cannot match, which justifies the price premium among nutraceutical, pharmaceutical, and cosmeceutical formulators. Buyers value batch-to-batch consistency, documented curcuminoid profiles, and compendial-grade specifications. As research tightens the link between dosing and effect, standardized extracts become the rational choice for products where efficacy claims must withstand regulatory and consumer scrutiny, anchoring long-term supply agreements.
- Growth Drivers
:
- Pharma 4.0: Partnerships like Novo Nordisk’s curcumin-coated diabetes drugs (launching Q4 2025) target a $4.3B anti-inflammatory drug market. Digitally integrated manufacturing, continuous-processing lines, and real-time quality analytics are enabling pharmaceutical-grade turmeric ingredients at commercial scale. Such collaborations legitimize the category for conservative prescribers and open reimbursement-adjacent channels, while signaling to ingredient suppliers that long-term contracts, validated supply chains, and full documentation will be decisive competitive advantages in the years ahead.
- Skincare Boom: Estée Lauder’s Golden Shield Serum (turmeric + blue light therapy) reduced wrinkles by 41% in trials, fueling a 29% CAGR in cosmeceuticals. Topical curcumin appeals to consumers seeking plant-derived brightening and anti-redness benefits without harsh synthetics. The convergence of dermatological research and clean-beauty branding has turned turmeric into a hero ingredient for serums, masks, and sunscreens, with formulators competing on stability, penetration, and sensory elegance rather than price alone, reinforcing the premium-extract narrative.
3. Emerging Trends Shaping the Industry
A. Sustainability and Ethical Sourcing
- Regenerative Farming: Brands like Pavitramenthe Organic achieve 100% USDA Organic certification by adopting zero-waste practices—upcycling 95% of byproducts into biodegradable packaging. Regenerative approaches go beyond avoidance of synthetic inputs to actively rebuild soil health, sequester carbon, and enhance biodiversity through crop rotation and cover cropping. By closing material loops on the farm, leaders demonstrate that premium quality and environmental stewardship are complementary rather than competing objectives, a narrative that resonates strongly with institutional buyers and sustainability-focused retailers auditing their upstream footprint.
- Carbon-Neutral Production: Blockchain-tracked Indian farms (e.g., Bareilly region) reduce CO2 emissions by 1.2kg per kg of turmeric produced. Distributed-ledger traceability allows brands to substantiate origin, labor conditions, and emissions with immutable records, answering mounting regulatory demands for due diligence. Carbon accounting is increasingly tied to procurement decisions, and suppliers that quantify and actively shrink their footprint gain preferred-vendor status with multinationals bound by science-based reduction targets and public ESG commitments.
B. Technological Advancements
- Nano-Encapsulation: Patented delivery systems (e.g., CurcuWin®) boost curcumin absorption by 300%, targeting a $2.1B bioavailability-enhancement sector by 2027. Encapsulation protects the fragile molecule from gastric degradation and directs it toward lymphatic uptake, effectively resolving the central weakness of legacy formulations. The consequent leap in realized efficacy unlocks therapeutic positioning and justifies premium pricing, while patent landscapes encourage continuous innovation in matrices, emulsions, and co-crystal engineering across the ingredient sector, deepening the moat for first movers.
- AI-Driven Cultivation: Predictive analytics optimize monsoon yield forecasts with 94% accuracy, mitigating climate risks in India and Southeast Asia. Machine-learning models ingest satellite imagery, soil sensors, and historical weather to advise planting windows, irrigation, and pest control, stabilizing both quality and volume. For supply-chain managers, improved forecast fidelity translates into smoother contracting, reduced spot-market exposure, and the ability to guarantee year-round supply to multinational customers wary of disruptive shortfalls caused by increasingly volatile growing seasons.
C. Regional Market Dynamics
- North America: Leads with 38% market share, driven by FDA GRAS approval for pediatric supplements (e.g., Gerber’s toddler formulas launching 2025). A mature supplement culture, strong retail distribution, and high disposable income underpin steady growth, while clinical-validation messaging resonates with health-professional recommendation channels. Private-label and branded players alike are investing in child-friendly delivery formats, broadening the consumer base and embedding turmeric into early-life nutrition routines that can build decades of category loyalty.
- Asia-Pacific: Turmeric IV drips paired with acupuncture in Shanghai clinics show 27% faster post-chemotherapy recovery, boosting medical-sector adoption. The region balances deep traditional knowledge with rapid modernization of clinical practice, creating hybrid protocols that attract medical tourism and research interest. Rising middle-class spending and domestic production scale position Asia-Pacific as both a consumption engine and an innovation hub for novel delivery and combination therapies that bridge heritage medicine and contemporary clinical standards.
- Europe: Sugar tax strategies (e.g., Ribena’s 45% sugar replacement with turmeric) save €100M annually while aligning with EU Green Deal sustainability goals. Reformulation toward functional, lower-sugar beverages illustrates how regulatory pressure and consumer health trends jointly expand turmeric use in mainstream food systems. Strict but predictable compliance frameworks reward suppliers able to meet documentation and sustainability criteria, consolidating demand around qualified organic sources and raising the floor for market entry.
4. Challenges and Strategic Solutions
- Supply Chain Fragmentation: Over 60% of organic turmeric is wild-harvested, risking overexploitation. Solutions include Fair for Life certifications and farmer cooperatives. Fragmented sourcing complicates traceability, quality assurance, and volume guarantees, while unmanaged wild collection threatens genetic diversity and local ecosystems. Structured programs that aggregate smallholders, provide agronomic training, and institute fair pricing create resilient upstream networks that protect both supply security and producer welfare, turning a systemic risk into a defensible competitive advantage for organized suppliers.
- Consumer Education: 42% of U.S. buyers remain unaware of curcumin’s anti-glycation benefits. Brands like Moon Juice leverage TikTok’s #GoldenImmunity trend to drive engagement. The gap between product availability and mechanistic understanding limits repeat purchase and dosage compliance; educational content that explains bioavailability, synergy with piperine, and realistic expectations converts curiosity into loyalty. Transparent labeling and clinician partnerships further shorten the learning curve for new users and reduce the returns and dissatisfaction associated with mismatched expectations.
- Price Volatility: Climate-induced yield fluctuations in India (2024’s 15% drop) spur vertical integration—Pavitramenthe’s AI-powered drying facilities cut waste by 30%. Weather extremes and commodity speculation expose buyers to sudden cost spikes that erode margins and disrupt formulations. Integrated operators that control drying, storage, and processing capture efficiency and buffer shocks, while forward contracts and diversified geographies help stabilize procurement for downstream manufacturers, making supply planning more predictable across volatile agricultural cycles.
5. Future Outlook (2025–2035)
By 2030, the organic turmeric market will bifurcate into two clearly defined tiers, each serving distinct customer needs and margin structures. This segmentation reflects maturation of the category: buyers no longer treat turmeric as a single commodity but as a spectrum of ingredients differentiated by potency, purity, and intended application. Understanding where value concentrates allows suppliers to allocate capital, certifications, and R&D toward the segments with the strongest structural tailwinds, rather than competing indiscriminately across a market that is rapidly stratifying along quality and efficacy lines.
- Mass-Market Powders: Focused on culinary and affordable supplements ($15B segment). This tier prioritizes volume, consistent color, and food-safety compliance, serving households, food manufacturers, and entry-level wellness consumers. Competition centers on price, reliable supply, and clean-label assurance rather than maximal curcumin concentration. Economies of scale and efficient logistics will define winners, while private-label expansion keeps the category broadly accessible and defends baseline demand against economic downturns that squeeze discretionary supplement spending.
- Premium Extracts: Targeting pharma and luxury skincare ($12B segment) with CRISPR-engineered curcumin strains (98% purity). This tier rewards scientific differentiation, intellectual property, and clinical validation. Precision breeding and advanced purification enable standardized, high-potency inputs that meet stringent regulatory dossiers. As personalized and prescription-adjacent applications grow, premium extracts capture disproportionate value despite representing a smaller share of tonnage, reshaping margin structures across the entire value chain toward knowledge-intensive production.
Key Growth Levers:
- Space Nutrition: NASA’s 2026 Mars missions will test turmeric tablets for radiation protection, opening a $480M aerospace nutraceutical niche. Extreme environments demand compact, stable, and multifunctional nutrients, and curcumin’s antioxidant and anti-inflammatory profile fits the brief. Beyond symbolism, such validation extends shelf-life and efficacy credibility that trickles down to terrestrial premium products, inspiring consumer confidence in turmeric’s protective health roles and creating a powerful halo effect for functionally positioned brands.
- Personalized Medicine: At-home DNA kits (e.g., 23andMe) will recommend turmeric dosages based on genetic inflammation markers, capturing 18% of the $7B wellness tech market. As diagnostics and supplements converge, dosing shifts from one-size-fits-all to biomarker-guided regimens, increasing compliance and outcomes. This data-driven model creates recurring revenue for brands and deepens the scientific narrative linking turmeric to individual health optimization, while generating proprietary insight that can inform future product development and targeting.

Organic turmeric extract and powder are transitioning from kitchen staples to multidisciplinary wellness cornerstones. With innovations in sustainability, bioavailability, and digital health integration, the sector is set to redefine global nutrition and medicine. Stakeholders must prioritize ethical sourcing, consumer education, and R&D to harness this $30B+ opportunity by 2035. Suppliers that invest in traceable organic supply, validated extraction, and transparent storytelling will be best positioned to capture durable share as the market matures from novelty to necessity across food, pharma, and personal-care value chains, while laggards face margin compression in an increasingly crowded and credentialed marketplace.
Recommended Products

Organic Turmeric Extract Powder
Organic Turmeric Powder & Extract Powder — dual-grade formats sourced from certified organic Curcuma…
Black Pepper Extract Powder
Black Pepper Extract Powder delivers ≥95% standardized piperine in a potent format.
Related Posts